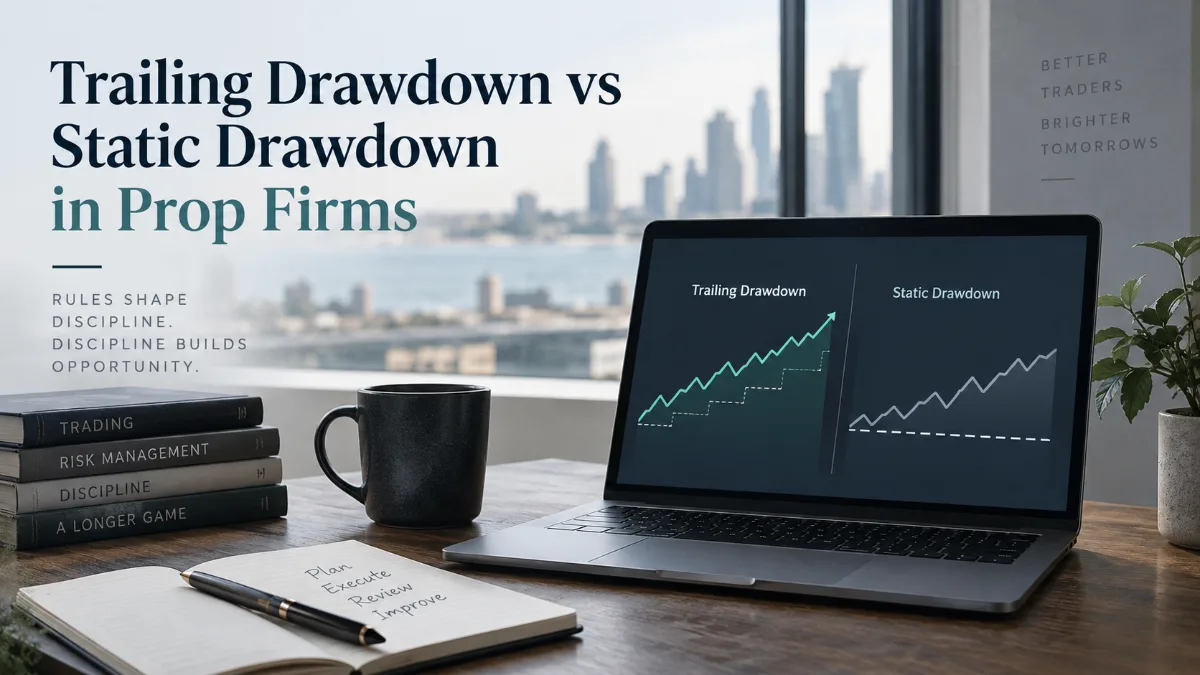
Static drawdown keeps the account's maximum loss floor fixed while trailing drawdown moves that floor upward as the account reaches new qualifying highs. That single difference changes how much room a trader has after making profits. Static drawdown generally becomes more forgiving as the account grows because the floor stays in place. Trailing drawdown can keep effective risk room tight until the trailing threshold reaches a lock point or stops moving under the firm's rules.
The headline drawdown amount alone is not enough to compare prop firm accounts. A $2,000 static drawdown and a $2,000 trailing drawdown can create very different trading conditions even when both begin at the same level. The result depends on the reference value, update timing, lock point and payout treatment.
Trailing drawdown vs static drawdown at a glance
| Feature | Static drawdown | Trailing drawdown |
|---|---|---|
| Loss floor | Normally stays fixed at its original level | Moves upward after qualifying account highs |
| Moves down after losses | No | No |
| Effect of profits | Usually increases the distance between balance and loss floor | May move the loss floor higher and preserve roughly the same risk distance |
| Intraday profit effect | Usually none on the maximum loss floor | Can matter if the rule trails real-time equity or intraday highs |
| End-of-day profit effect | Usually none on the maximum loss floor | Often matters under end-of-day trailing models |
| Typical planning challenge | Protecting a fixed reserve | Tracking a moving breach level |
| Potential benefit after account growth | More absolute cushion above the floor | Depends on the trail and its lock point |
These descriptions are models rather than universal contract terms. A prop firm can define its own calculation method. Before trading an evaluation or funded account, the operative rule is the firm's current account agreement and rule documentation.
What is static drawdown?
Static drawdown is a maximum loss rule in which the breach threshold is set from an initial reference value and normally does not rise when the account becomes profitable. If a $50,000 account has a $2,000 static maximum drawdown, the initial floor is $48,000. If the balance later rises to $53,000, the floor is still $48,000 unless another rule changes it.
Profitable trading can therefore create additional cushion. At a $50,000 balance the trader has $2,000 above the static floor. At $53,000 the distance is $5,000. That does not mean $5,000 should be risked. It means the maximum loss rule has become less restrictive relative to the larger balance.
A static drawdown is usually easier to model because the threshold remains stable. Other controls can still bind first, including a daily loss limit, position-size limit, consistency rule or payout condition.
How trailing drawdown works
A trailing drawdown starts with a loss floor below the account's initial reference value and moves that floor upward when the account establishes a new qualifying high. The floor does not normally move back down after losses. In simplified form, the moving threshold equals the highest qualifying account value minus the permitted drawdown distance until a stated lock point is reached.
Consider a $50,000 account with a $2,000 trailing drawdown. The initial floor is $48,000. If the relevant account high becomes $50,600, the floor can rise to $48,600. If the qualifying high then reaches $51,400, the floor can rise to $49,400. A later loss does not normally restore the old $48,000 floor.
The crucial phrase is qualifying high. Different rules can use different reference values. A firm may trail the highest closed balance, an end-of-day balance, real-time equity or another defined value. Two accounts that both advertise a $2,000 trailing drawdown can therefore behave differently during the same sequence of trades.
Many trailing structures also have a lock point. A rule may stop moving once the floor reaches the original starting balance. The drawdown is then dynamic early in the account but effectively fixed after sufficient profit. Other programs can use a different lock level or continue trailing. The stop point is a key term to verify.
Intraday trailing and end-of-day trailing
Trailing drawdown becomes much easier to understand when it is separated into intraday and end-of-day models. The difference is the timing of the reference update.
Intraday trailing drawdown
Intraday trailing can react while trades are still open. If the rule follows real-time equity, an unrealized profit may raise the high-water mark and move the drawdown floor upward before the trade is closed. If price then reverses, the floor may remain at the higher level even though the unrealized profit disappeared.
For example, start with $50,000 and a $2,000 trailing distance. An open trade pushes equity to $51,500. Under a pure real-time equity trail the floor can move to $49,500. If the trade later closes with the account at $50,400, the trader may have only $900 of room above that $49,500 floor. The account booked a profit but its remaining cushion became smaller than a trader who looked only at the closing balance might expect.
End-of-day trailing drawdown
End-of-day trailing generally updates from a value recorded at the firm's defined session close rather than from every intraday peak. Using the same starting balance and $2,000 distance, suppose equity briefly reaches $51,500 but the account closes the session at $50,400. If the rule trails the closing balance, the next floor would be $48,400 rather than $49,500.
This makes end-of-day trailing less sensitive to temporary open profits than real-time equity trailing. It is still a moving threshold, and profitable closes can keep lifting the floor until the applicable lock rule is reached.
A worked comparison with the same account
Assume two traders each start with a nominal $50,000 account and a $2,000 maximum drawdown. One account uses static drawdown. The other uses a trailing drawdown based on the highest eligible balance. Ignore daily loss rules for the moment so the effect of the maximum drawdown can be isolated.
| Account event | Balance | Static floor | Trailing floor |
|---|---|---|---|
| Start | $50,000 | $48,000 | $48,000 |
| Profit raises reference high | $51,000 | $48,000 | $49,000 |
| New reference high | $51,700 | $48,000 | $49,700 |
| Loss after the high | $50,600 | $48,000 | $49,700 |
After the final row the static account has $2,600 above its floor while the trailing account has only $900. Both are still $600 above the original starting balance, yet their remaining risk capacity is very different. Advertised account size and maximum loss amount alone can therefore mislead.
If the trailing rule locks when the floor reaches $50,000, further profits may then create additional cushion much like a static rule. The tighter phase is often the period before that lock point.
Why a trailing drawdown can feel tighter after a winning trade
A winning trade can increase the account value and simultaneously move the permissible loss floor upward. That creates a counterintuitive result: the trader made money but may not have gained equivalent room to absorb a future loss.
Suppose the allowed trail is $2,000. If the qualifying account high moves from $50,000 to $51,000, the loss floor also rises by $1,000 under a simple trailing model. The distance between the new high and the floor remains $2,000. With a static floor the same $1,000 gain would increase the cushion from $2,000 to $3,000.
This distinction matters for strategies with volatile open profits. A trader who lets winners fluctuate widely can face a tighter path under an intraday equity trail. A trader who closes gains steadily and keeps trade risk small may find a trailing model more manageable.
Balance and equity can change the result
Balance usually refers to realized account value after closed trades. Equity generally includes the effect of open positions. A drawdown rule based on equity can therefore trigger even when the closed balance still looks safe.
Imagine a closed balance of $50,500 and a breach floor of $49,500. If open positions show a $1,050 loss, equity is $49,450. An equity-based rule can treat that as a breach even though the closed balance remains above the threshold. By contrast, a balance-only rule may not react until losses are realized, subject to any separate liquidation or margin controls.
Never infer the measurement basis from the word "drawdown." Check whether the rule uses balance, equity, net liquidation value, realized P&L or another defined figure and whether commissions or fees count.
Daily loss limits are a separate constraint
Maximum drawdown and daily drawdown answer different questions. Maximum drawdown sets the account's overall failure floor. A daily loss limit restricts how much the account may lose during a defined trading day or session. An account can remain comfortably above its maximum drawdown threshold and still violate the daily rule.
The reset method also matters. A daily limit can use the previous session's balance, equity or another reference. Some firms treat a hit as failure while others use temporary liquidation or lockout. Do not merge daily and maximum rules simply because both use the word "drawdown."
How payouts and withdrawals affect drawdown room
Payouts can materially change the relationship between the account balance and its loss floor. A payout removes value from the account. If the drawdown threshold stays unchanged, the remaining cushion can shrink immediately. Some programs also reset or lock the maximum loss limit when a payout occurs.
For example, suppose an account has a $54,000 balance and a $50,000 locked loss floor. Before a payout the distance is $4,000. If the trader withdraws $3,000 and the floor remains $50,000, the post-payout balance is $51,000 and the cushion falls to $1,000. The payout was not a trading loss, but it changed how much room remains before the account reaches its threshold.
Payout policy and drawdown policy should therefore be read together. A payout can be unattractive if it leaves the account too close to its breach level for normal position sizing.
Which drawdown structure is easier to trade?
For pure loss-floor flexibility, static drawdown is usually easier because profitable account growth increases the distance above a fixed threshold. That does not automatically make a static account a better product. Fees, profit targets, payout rules, daily limits, permitted instruments and other restrictions can outweigh the drawdown advantage.
Among trailing models, end-of-day trailing is generally easier to plan around than real-time equity trailing because temporary intraday profits do not necessarily raise the floor. The exact reference calculation and lock point still matter.
Trading style matters too. A strategy that frequently gives back open profit can be especially sensitive to an intraday equity trail.
How to compare prop firm drawdown rules
Use the advertised drawdown percentage or dollar amount only as the starting point. A complete comparison should answer the following questions before the account is purchased or traded:
- What is the initial breach level? Calculate the actual dollar floor from the starting reference value.
- Is the maximum drawdown static or trailing? Do not assume a label such as maximum loss tells you how the floor behaves.
- What value drives the calculation? Identify whether the rule uses closed balance, equity, net P&L or another measure.
- When does a trailing floor update? Determine whether it moves intraday, after closed trades or only at the end of the firm's defined session.
- Does the floor ever stop trailing? Find the lock point and determine whether it is the starting balance, a level above it or another threshold.
- What happens at the boundary? Check whether touching the threshold counts as a breach or whether the account must move below it.
- How do fees affect the calculation? Commissions, platform fees or other trading costs may influence balance or equity.
- How do payouts change the floor? Model the post-payout balance and remaining cushion before requesting money.
- What other rules can fail the account first? Compare daily loss, position size, consistency and prohibited-strategy rules alongside maximum drawdown.
A useful comparison metric is usable risk room after profit, not just initial drawdown. Model the account after a realistic winning period and payout to see how much operating room actually remains.
Common mistakes with trailing drawdown
- Treating open profit as permanent cushion. Under an intraday equity trail, open profit can raise the floor before it is realized.
- Assuming the threshold falls after a losing trade. A trailing floor normally moves in one direction. Losses reduce the account value without restoring earlier room.
- Ignoring the session definition. End-of-day does not necessarily mean midnight in the trader's local time. The firm can define its own trading session boundary.
- Forgetting the lock point. The rule before and after the lock point may create very different risk conditions.
- Using the full remaining drawdown as a trade stop. Leaving no buffer exposes the account to slippage, fees and ordinary price movement near the limit.
- Confusing maximum drawdown with market margin. A prop firm's evaluation loss rule is a contractual risk parameter. It is not the same concept as exchange or broker margin requirements.
Risk management still matters more than the label
Neither static drawdown nor trailing drawdown makes leveraged trading safe. The Commodity Futures Trading Commission notes that futures trading is volatile and risky and that leverage can magnify losses. A prop firm's loss threshold can limit participation in its program, but it does not remove market risk or guarantee that a strategy has positive expectancy.
Convert the drawdown rule into a personal risk budget. If only $2,000 of room remains, risking $1,500 on one trade leaves little tolerance for adverse movement or execution costs. Smaller per-trade risk leaves more room before the contractual floor becomes relevant.
Static drawdown or trailing drawdown: what should you choose?
Choose based on the full rule set rather than the drawdown name alone. Static drawdown suits traders who value a fixed failure floor and want profits to build cushion. Trailing drawdown can still be workable when its update method and lock point fit normal trade risk.
The strongest comparison is numerical. Take your expected position size, typical stop distance, normal daily loss and likely payout amount. Then run the same trading path through each firm's formula. If one account would leave $3,000 of room while another would leave $900 after the same sequence, that difference is more meaningful than the nominal account size printed on the offer.
For trailing drawdown vs static drawdown, the core rule is simple: static drawdown protects a fixed floor while trailing drawdown protects an increasingly higher floor as qualifying profits are made. The decision depends on what moves that floor, when it moves and when it stops. Those mechanics determine the real risk capacity of the account.