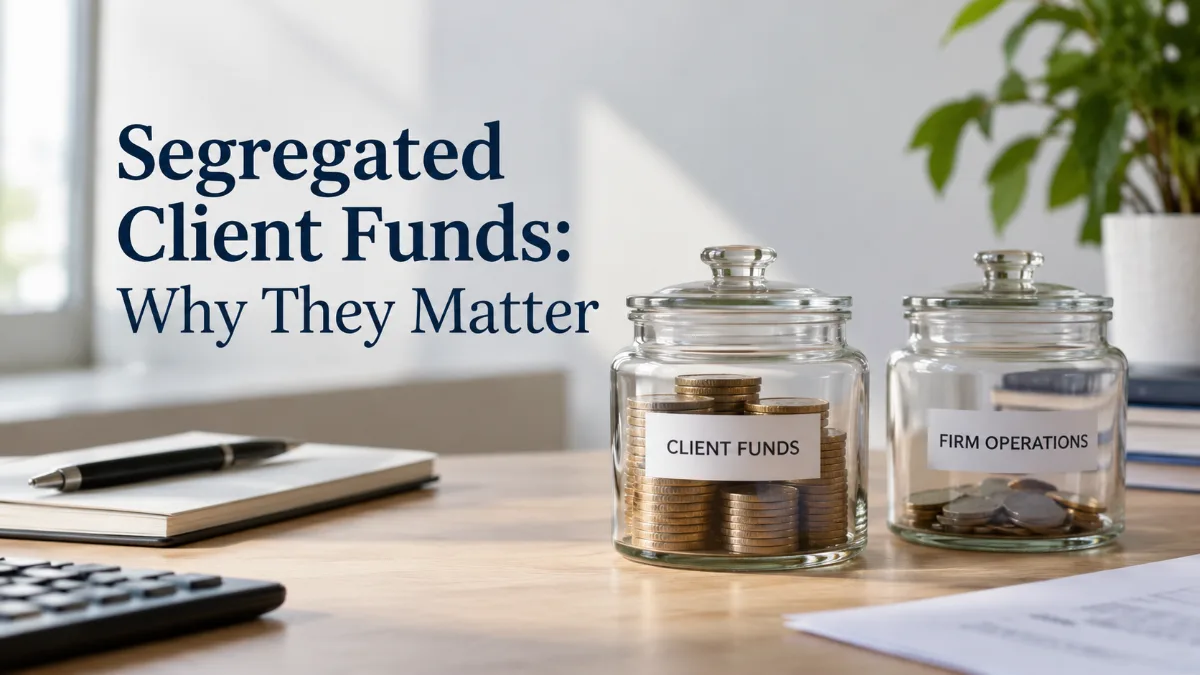
Segregated client funds are money that a broker or investment firm holds for clients separately from the firm's own operating money. The central purpose is to reduce the risk that customer money is treated like ordinary corporate cash. If a broker is allowed to mix client deposits with money used for payroll, marketing, rent or other business expenses, the client's exposure extends beyond trading risk to the broker's everyday financial condition.
That makes segregation an important safeguard, but not an absolute guarantee. A properly operated client money arrangement can help identify what belongs to customers and restrict how a firm may use it. It does not eliminate market losses, fraud, recordkeeping failures, banking risk or every complication that can arise during insolvency. The practical protection depends on the broker's legal entity, regulator, product, client classification and the rules that apply to the account.
What are segregated accounts?
In brokerage, segregated accounts are accounts used to keep eligible client funds distinct from the broker's own money. The bank account may be opened in the broker's name with wording that identifies it as a client account, trust account or another protected account type required by local law. The important point is not simply the label. The legal and operational arrangements must make the client money distinguishable from corporate funds.
Segregation usually happens at the level of the broker and its clients as a group. It does not necessarily mean every customer receives a separate bank account in that customer's own name. Many firms use an omnibus client account that contains money belonging to multiple clients while internal ledgers record each customer's entitlement. Some structures allow or require more individualized segregation, but that is a different concept from basic separation between client money and the firm's own assets.
The Financial Conduct Authority states that firms subject to its Client Assets Sourcebook must follow client asset rules when holding or controlling client money, with the objective of keeping client money and assets safe if firms fail and exit the market. The FCA's client money rules also describe segregation of client money from a firm's own money as an important safeguard.
How segregated client funds work
Money is separated from operating cash
The broker receives money that qualifies as client money and places it into the account structure required by the applicable rules. Corporate money used to run the business is kept outside that client money pool except where the rules permit limited adjustments for operational purposes. The broker should therefore be able to distinguish what belongs to customers from what belongs to the firm.
This distinction matters because a broker is not supposed to finance ordinary business activity with protected client balances. In the European Union, European Securities and Markets Authority materials reflecting MiFID II require investment firms holding client funds to make arrangements that safeguard clients' rights and prevent use of those funds for the firm's own account, subject to the legal framework that applies to the firm.
Internal records identify each client's entitlement
When several customers' funds are held in one pooled account, the bank balance alone does not show how much belongs to each person. The broker's books and records must do that work. A sound client money system therefore depends on accurate transaction records, allocation procedures and reconciliations between the firm's internal ledger and external bank balances.
This is why the phrase "funds are segregated" should never be interpreted as a description of a single bank transfer. Segregation is an ongoing control process. Deposits, withdrawals, fees, realized trading results and other permitted movements constantly change what the firm owes clients. The records have to keep pace with those changes.
Third parties may still be involved
Client money can sometimes move beyond the broker's primary client bank account when transactions require payment to a clearing firm, liquidity arrangement, custodian or another permitted third party. Whether that is allowed and what protection continues to apply depend on the product and jurisdiction. A claim that money is segregated at the broker therefore does not automatically explain what happens to every dollar once a trade is opened or settled.
Why client funds segregation matters
The main benefit of segregation is legal and operational separation. It creates a clearer boundary between money held for clients and money belonging to the broker. That boundary can reduce misuse risk during normal operations and make ownership claims easier to identify if the firm enters administration or another insolvency process.
Segregation also supports supervisory controls. Regulators can require firms to maintain designated accounts, reconcile balances, keep records and report client money information. In Australia, the Australian Securities and Investments Commission explains that a client money account under the relevant rules is generally operated as a trust account and that firms holding reportable client money must keep records and perform reconciliations. Reconciliation compares what the firm's records say it should hold with the amount actually held in the client money account, helping expose discrepancies that require investigation.
| Risk or issue | What segregation can do | What it cannot guarantee |
|---|---|---|
| Broker operating expenses | Separates protected client funds from normal corporate cash | It cannot stop misconduct if controls are deliberately breached |
| Broker insolvency | Helps identify funds held for clients rather than for the firm | It does not guarantee immediate or full repayment in every insolvency |
| Trading losses | Keeps account custody separate from the broker's own finances | It does not protect against losses caused by market movements |
| Bank or custodian problems | Can require the broker to use eligible institutions and defined account structures | It does not remove all third-party credit or operational risk |
| Recordkeeping errors | Reconciliation rules can help detect discrepancies | Segregation alone cannot prevent inaccurate books or fraud |
What a segregated funds broker claim really means
The phrase segregated funds broker is commonly used in broker marketing, but it is not enough by itself to establish how customer money is protected. Two brokers can both say that client funds are segregated while operating under different laws, account structures and insolvency regimes.
A useful assessment starts with the exact regulated entity that will hold the account. Large broker groups often operate several subsidiaries. A website may display a well-known regulatory license while a particular customer is actually onboarded by another affiliate in a different country. The client agreement, account-opening page and regulatory register should identify the contracting entity clearly.
You should then determine what the regulator's client money rules require for that entity and product. The answer may differ for securities, futures, CFDs, spot foreign exchange, professional clients and other categories. Some funds may qualify as protected client money while other balances or transfers may fall outside the same regime. Marketing language should never replace the legal terms governing the specific account.
What segregation does not protect you from
Segregated accounts reduce one category of financial risk, but they do not turn a broker account into a risk-free deposit. Several exposures remain important.
- Market risk: Money lost because a position moves against you is not restored by segregation.
- Execution risk: Slippage, gaps, rejected orders or poor execution quality are separate from client money custody.
- Fraud or control failures: A dishonest or badly managed firm can breach rules, falsify records or move money improperly.
- Third-party risk: Client funds may be held with banks, custodians or other institutions whose failure can create additional complications.
- Shortfalls: If records and actual balances do not match, the client money pool may have a deficiency that must be resolved under local insolvency law.
- Access delays: Even when ownership is clear, an insolvency administrator may need time to reconcile accounts and determine valid claims.
- Product exclusions: Not every payment to a broker necessarily receives the same client money treatment.
Segregation is also different from an investor compensation scheme. A compensation scheme may provide eligible customers with protection if defined conditions are met, while segregation governs how client money is held and treated. The existence of one does not automatically prove the existence or scope of the other.
How to verify a broker's client money protections
- Identify the legal entity. Find the company name that will appear in your client agreement. Do not rely only on the trading brand.
- Verify the license. Search the regulator's official register and confirm the entity name, license status and permitted activities.
- Read the client money section. Look for terms explaining whether money is held in segregated accounts, trust accounts or another protected structure.
- Check the product scope. Confirm that the rules apply to the instrument you intend to trade and to your client classification.
- Ask where funds are held. A broker should be able to explain the type of institution used and whether client money is pooled or individually segregated.
- Review permitted uses. Look for provisions covering transfers to third parties, margin arrangements, fees, interest and circumstances in which money stops being treated as client money.
- Read the insolvency language. Find out how the agreement describes client claims if the broker fails and whether a compensation mechanism may apply.
The strongest evidence is regulatory status plus clear contractual terms that match the regulator's rules. A badge on a homepage, a statement such as "top-tier banks" or an unsupported claim that funds are "100% safe" should carry little weight without verifiable details.
Red flags in client fund claims
- The broker says funds are segregated but does not name the regulated entity holding the account.
- The website displays several licenses without explaining which one applies to your account.
- The client agreement gives the firm broad rights to use customer money without explaining the legal basis.
- The broker guarantees that segregated funds can never be lost.
- Deposit instructions direct money to unrelated companies or personal accounts.
- The broker refuses to explain whether client money is pooled with other customers.
- The firm describes segregation as if it were the same as government deposit insurance or investor compensation.
- Regulatory register information does not match the website's legal name or domain details.
Any one red flag deserves investigation. Several together can indicate that the marketing claim is stronger than the actual protection.
What happens to segregated accounts if a broker fails?
In a properly structured client money regime, the objective is to keep protected client funds identifiable and separate from the broker's general corporate assets. That can improve the position of clients compared with ordinary unsecured creditors because the money is not intended to be treated simply as property available for the firm's business debts.
Recovery can still be complex. Administrators may need to confirm account balances, reconcile the firm's records, investigate disputed transactions and determine which customers are entitled to the client money pool. If there is a shortfall, local rules decide how losses are allocated. The applicable law also determines whether administration costs, compensation arrangements or other protections affect the eventual amount and timing of repayment.
For that reason, "segregated" should be understood as a risk-control mechanism rather than a promise of instant access after failure. It improves the structure around client ownership, but the quality of records and the legal framework still matter.
Do segregated accounts work the same everywhere?
No. The broad principle of separating client money from firm money appears in multiple regulatory systems, but the implementation varies. Differences can include who must use segregated accounts, which products qualify, where money may be deposited, whether pooled accounts are permitted, how often reconciliations occur and what happens after insolvency.
| Question to compare | Why it matters |
|---|---|
| Which legal entity holds the account? | Protection follows the regulated entity and its jurisdiction rather than the brand name alone. |
| Which balances qualify as client money? | Some payments or transfers may receive different legal treatment. |
| Is the account pooled or individualized? | Pooled segregation separates clients collectively from the broker while individual segregation can separate one client's assets from others. |
| Where may funds be deposited? | Approved institutions and diversification requirements can affect third-party exposure. |
| What happens on insolvency? | Claim procedures and treatment of any shortfall depend on local law. |
| Is compensation available? | Eligibility and coverage are separate from the basic segregation requirement. |
This jurisdictional variation is why broker comparisons should focus on the actual account-opening entity rather than making a simple regulated versus unregulated distinction. Regulation matters greatly, but the substance of the relevant client money regime matters too.
Common questions about segregated accounts
Is my money kept in a bank account with my own name?
Not necessarily. Many brokers use pooled client accounts. Your share of that pool is tracked through the broker's internal records. Individual client segregation is a more specific arrangement and should not be assumed unless the broker's terms say it applies.
Can a broker trade with segregated client money?
Rules in well-developed client money regimes generally restrict a firm from treating protected client funds as its own working capital. However, permitted transfers connected with transactions can vary by product and jurisdiction. The client agreement and regulator's rules determine the exact answer.
Does segregation mean withdrawals are guaranteed?
No. Segregation concerns custody and legal separation. A withdrawal can still be delayed by compliance checks, payment processing, bank issues, disputes or insolvency. Persistent unexplained withdrawal obstruction is a separate risk signal and should not be excused merely because the broker claims to use segregated accounts.
Are segregated funds the same as insured deposits?
No. A broker's client money arrangement and a bank deposit insurance scheme are different legal protections. Whether a deposit protection or investor compensation scheme applies depends on the institution, account structure, jurisdiction and eligibility rules.
How much weight should segregation have when choosing a broker?
Segregated client funds should be treated as a baseline safety criterion for a broker that is required to hold customer money under a regulated client money regime. They are more meaningful when the broker can be matched to an active license, the relevant rules clearly require separation and the client agreement explains how the arrangement works.
Segregation should not be used as a shortcut for evaluating the entire broker. Capital adequacy, regulatory history, withdrawal practices, execution model, complaints procedures, cybersecurity, pricing and the financial strength of relevant counterparties can also affect risk. A broker can comply with segregation rules and still be unsuitable for other reasons.
The most useful question is therefore not simply "Does this broker segregate client funds?" Ask which entity holds my money, under which rules, in what account structure and with what protection if the firm fails? A broker that can answer those questions clearly provides more decision-relevant information than one that repeats the word "segregated" without explaining the legal and operational details behind it.