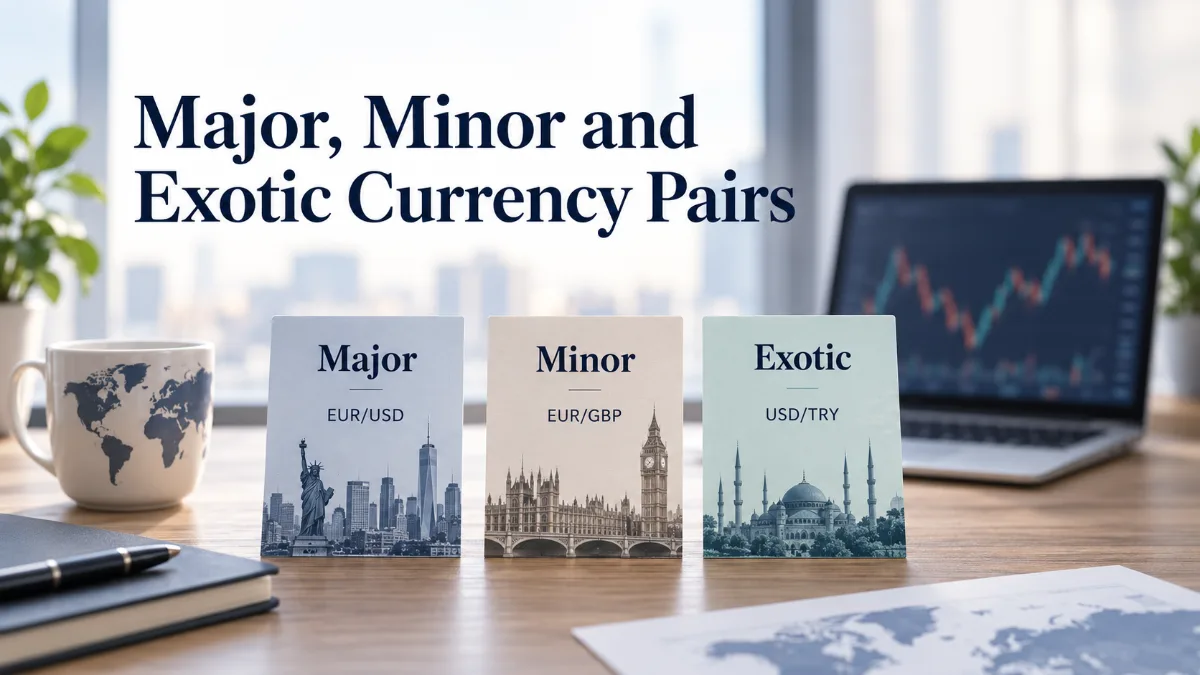
A currency pair is the price of one currency expressed in another currency. Traders commonly group currency pairs into major pairs, minor pairs and exotic pairs. The categories are useful because they often signal differences in liquidity, trading activity, spread behavior and sensitivity to market events. They are conventions rather than a single official classification system, so the exact list can differ among brokers, data providers and market participants.
The distinction matters most when comparing trading conditions. Major currency pairs generally combine the US dollar with another heavily traded currency. Minor pairs usually combine two widely traded currencies without the US dollar. Exotic pairs normally combine a major or highly traded currency with a currency that has lower global turnover or more concentrated liquidity. Those differences can affect the bid-ask spread, execution quality, volatility and the cost of keeping a position open.
What Is a Currency Pair?
Every forex quote contains two currencies. The first is the base currency and the second is the quote currency. In EUR/USD, the euro is the base currency and the US dollar is the quote currency. If EUR/USD is quoted at 1.1000, one euro is priced at 1.1000 US dollars.
A pair moves because the value of one currency changes relative to the other. A rise in EUR/USD means the euro has strengthened against the dollar, the dollar has weakened against the euro, or both forces are acting at the same time. This relative structure is why currency analysis always involves two economies, two interest-rate environments and two sets of market expectations.
Currency pairs are normally quoted with a bid and an ask price. The bid is the price at which the market or dealer will buy the base currency, while the ask is the price at which it will sell it. The difference is the spread. Investor.gov describes the bid-ask spread as an inherent trading cost: a wider spread makes entering and exiting a position more expensive before other commissions or charges are considered.
How Major Pairs Are Defined
In retail forex usage, a major pair usually contains the US dollar and one of the other heavily traded developed-market currencies. A widely used list includes EUR/USD, USD/JPY, GBP/USD, USD/CHF, USD/CAD, AUD/USD and NZD/USD. These pairs are often treated as a practical group because they are heavily followed, commonly quoted and supported by deep dealer liquidity.
That list should not be mistaken for an official ranking of the world's largest currency pairs. Market structure changes over time, and global turnover data does not always match the traditional retail label. The Bank for International Settlements reported that global foreign exchange turnover averaged $9.6 trillion per day in April 2025. The US dollar was on one side of 89.2% of trades, and all of the ten most traded currency pairs involved the US dollar. The same data also shows the growing importance of pairs such as USD/CNY, which may not appear on every broker's traditional list of seven majors.
This is the most useful way to interpret the term major pairs: it describes a high-liquidity market convention, not a permanent legal category. If a platform labels a different set of pairs as majors, check what the label is being used for. It may affect product menus, margin schedules or spread tables rather than describe a universal market standard.
Major Pairs and Their Typical Characteristics
| Pair | Base currency | Quote currency | Typical market feature |
|---|---|---|---|
| EUR/USD | Euro | US dollar | Very deep global liquidity and intense dealer competition |
| USD/JPY | US dollar | Japanese yen | Strong sensitivity to US and Japanese rates |
| GBP/USD | Pound sterling | US dollar | High liquidity with potentially sharp macroeconomic reactions |
| USD/CHF | US dollar | Swiss franc | Closely watched during shifts in global risk sentiment |
| USD/CAD | US dollar | Canadian dollar | Often influenced by North American growth and commodity conditions |
| AUD/USD | Australian dollar | US dollar | Responsive to global growth and commodity-linked themes |
| NZD/USD | New Zealand dollar | US dollar | Smaller market than the largest majors but still widely traded |
Major pairs tend to have tighter spreads than less liquid pairs under normal market conditions because many banks, market makers and other participants compete to trade them. Deep liquidity can also make it easier to execute larger orders with less price impact, although no pair is immune to slippage or sudden spread expansion.
Liquidity is not constant throughout the day. A major pair can trade very efficiently during active sessions and become thinner around market transitions, holidays or periods of unusual uncertainty. Economic releases, central-bank decisions and unexpected geopolitical events can widen spreads even in EUR/USD or USD/JPY. The category therefore describes typical market depth, not a promise of a fixed transaction cost.
What Are Minor Currency Pairs?
Minor currency pairs usually combine two widely traded currencies without the US dollar. They are also commonly called cross currency pairs or simply crosses. Examples include EUR/GBP, EUR/JPY, GBP/JPY, EUR/CHF, AUD/JPY and AUD/NZD.
The terms minor and cross overlap but are not always identical. A cross technically describes a pair that does not contain the US dollar. Some market participants use "minor" more narrowly for crosses made from the currencies that also appear in the traditional major-pair set. Under that convention, EUR/JPY is a minor pair, while a less frequently traded non-dollar cross could be categorized separately.
Minor pairs can still be highly liquid. EUR/GBP and EUR/JPY, for example, connect currencies with substantial international turnover. Their spreads are often wider than the most liquid dollar majors but can remain relatively competitive. Other crosses may have thinner order flow, larger intraday gaps or more variable spreads.
Cross rates are also linked mathematically to dollar pairs. If EUR/USD is 1.1000 and USD/JPY is 150.00, a consistent EUR/JPY price is approximately 165.00 because 1.1000 multiplied by 150.00 equals 165.00. In active markets, arbitrage keeps direct cross quotes close to the rates implied by their component pairs after transaction costs. This relationship explains why news that moves a dollar pair can still affect a minor pair indirectly. It also shows why a cross should not be treated as isolated from the broader FX market. For traders, the practical point is that a minor pair can express a cleaner relative view between two non-dollar currencies while remaining connected to the liquidity and repricing of the larger dollar-centered market.
Crosses can be useful when a trader wants exposure to a relative view that does not directly involve the US dollar. Someone comparing the euro area with the United Kingdom may prefer EUR/GBP rather than opening separate EUR/USD and GBP/USD positions. This can make the economic thesis cleaner, but the pair still reflects its own liquidity conditions and pricing conventions.
What Makes a Pair Exotic?
An exotic currency pair generally combines a major or highly traded currency with a currency that has lower global turnover, more locally concentrated liquidity or different market-access conditions. Common examples include USD/TRY, USD/ZAR, USD/MXN, USD/BRL and USD/THB. Depending on the venue, pairs involving currencies from Central Europe, Asia, Latin America, Africa or the Middle East may also be described as exotic.
The word "exotic" is market terminology, not a judgment about an economy or the quality of its currency. It also covers a wide range of markets. The Mexican peso and South African rand can have substantial institutional trading activity, while other currencies may trade much less frequently outside their domestic market. Treating all exotic pairs as equally illiquid would therefore be misleading.
An exotic classification can also depend on the trader's venue and region. A currency that is routinely traded by domestic banks may look much less liquid on an international retail platform. Capital controls, local market hours, settlement conventions and access to deliverable currency can further change how a pair is quoted. For this reason, the label is best used as an initial liquidity clue rather than a complete description of execution risk.
Major Minor and Exotic Pairs Compared
| Category | Typical structure | Typical liquidity | Typical spread behavior | Examples |
|---|---|---|---|---|
| Major | USD plus another heavily traded currency | High to very high | Usually the tightest under normal conditions | EUR/USD, USD/JPY, GBP/USD |
| Minor | Two widely traded currencies without USD | Moderate to high | Often wider than top majors | EUR/GBP, EUR/JPY, GBP/JPY |
| Exotic | Highly traded currency plus a lower-turnover currency | Varies from moderate to thin | Often wider and more variable | USD/TRY, USD/ZAR, USD/BRL |
The table describes common tendencies rather than fixed rules. A liquid minor can trade with a tighter spread than a less active major at a particular moment. An exotic pair can also become very active during local market hours. What matters for an actual trade is the live bid and ask, available depth, order size and current market conditions.
Why Exotic Pairs Have Wider Spreads
The exotic pairs spread is usually wider because liquidity providers face a different balance of trading volume, inventory risk and hedging cost. If fewer participants are willing to quote both sides of a market, dealers have less competition and may need more compensation for holding a position that is harder to offset quickly.
Several factors can widen spreads in exotic currency pairs:
- Lower continuous liquidity: fewer orders may be available near the current market price.
- Higher volatility: rapid price changes increase the risk of quoting a price that becomes stale before execution.
- Limited market hours: liquidity may be strongest during the local trading day and weaker outside it.
- Funding and hedging costs: market makers may face higher costs when financing or offsetting exposure.
- Event risk: policy changes, elections or unexpected central-bank action can sharply change available liquidity.
- Venue differences: retail spreads depend partly on the dealer or platform and may not mirror institutional interbank conditions.
Spread size should be evaluated as a cost relative to expected price movement. A spread of several pips may be minor for a position targeting a large move, while the same cost may make a short-term strategy uneconomic. The monetary cost also depends on position size and pip value, so comparing pairs only by the number of pips can be misleading.
How Liquidity Changes Trading Conditions
Liquidity affects more than the quoted spread. It influences how much volume can trade near the displayed price, how quickly orders can be matched and how much an order may move the market. A narrow spread with little depth can still produce poor execution for a large order, while a slightly wider spread in a deeper market may deliver more predictable fills.
Slippage becomes especially important during fast markets. A stop order or market order does not guarantee execution at the last price seen on a screen. If available quotes move before the order reaches the market or dealer, the fill can occur at a different level. This risk exists in majors, minors and exotics, but it can be more pronounced where liquidity is thinner.
Retail traders should also distinguish the underlying currency market from the trading venue. In US off-exchange retail forex, the Commodity Futures Trading Commission notes that customers trade against their dealer rather than on an open exchange, and that the dealer controls the prices and conditions available on its platform. This is one reason live spreads and execution policies should be compared at the venue level rather than assumed from a pair's category alone.
How to Choose a Currency Pair
The major minor exotic pairs framework is most useful as a screening tool. It can help narrow the market, but it should not decide a trade by itself. A sensible comparison considers the cost of execution together with the economic drivers of the pair.
- Check the live spread. Compare the bid and ask during the hours when you expect to trade. Do not rely only on an advertised minimum spread.
- Match the pair to the trading horizon. Short-term strategies are generally more sensitive to spread and slippage than positions that target larger multi-day moves.
- Know the active session. A pair often has better liquidity when the financial centers most connected to its currencies are open.
- Review event exposure. Central-bank meetings, inflation releases, employment data and political events can change volatility and liquidity abruptly.
- Understand financing. Holding a leveraged forex position can create overnight financing charges or credits. Large interest-rate differences can make this especially significant in some exotic pairs.
- Check position sizing. Wider spreads and sharper gaps can increase the amount of capital at risk around entry, exit and stop execution.
For a beginner, highly liquid major pairs are often easier to observe because pricing is more competitive and market information is abundant. That does not make them low risk. Leverage can magnify small exchange-rate movements, and major pairs can move sharply after unexpected news. Exotic pairs add further complexity because transaction costs, financing and liquidity conditions may change more dramatically.
Common Classification Mistakes
One common mistake is assuming that every pair containing the US dollar is automatically a major. USD/TRY and USD/BRL contain the dollar but are normally described as exotic pairs. The identity of the second currency and the depth of the market matter.
Another mistake is treating every non-dollar pair as a minor. Many liquid crosses fit the minor category, but a non-dollar pair involving a lower-turnover currency may still have exotic characteristics. The absence of USD describes a cross, not necessarily its liquidity tier.
A third mistake is using the category as a substitute for live trading data. "Major" does not guarantee a one-pip spread, and "exotic" does not imply that a pair is always untradeable. Spreads change with time of day, volatility, dealer pricing and order size. The quote available when the order is placed is more important than a static category label.
It is also misleading to infer expected returns from the label. A major pair is not inherently more profitable, and an exotic pair does not offer better returns simply because its daily range or interest-rate differential is larger. Greater movement can come with wider spreads, larger gaps, higher financing costs and greater execution uncertainty.
Do Currency Pair Categories Change?
Yes. Currency-pair classifications can evolve as global trade, capital flows, monetary systems and market infrastructure change. A currency can gain international usage and deeper liquidity, while another can lose turnover. Broker classifications can also change for operational reasons even when the broader market structure has not changed dramatically.
The most durable distinction is therefore functional. Major pairs usually offer the deepest and most competitive trading conditions. Minor pairs provide direct exposure between widely traded non-dollar currencies. Exotic pairs generally involve less uniform liquidity and wider transaction costs. Use those labels to understand the likely market structure, then verify the actual spread, depth, volatility and financing conditions before treating any pair as suitable for a strategy.